From YouTube and AR glasses to USDC: Circle’s Nikhil Chandhok on building the dollar for everyone with a phone
After two decades building consumer products at Google, YouTube and Meta, Circle’s product and technology chief argues the winning stablecoin will simply be the one easiest to use.
Nikhil Chandhok built AR glasses at Meta, launched YouTube on the first iPhone, and co-founded Google Blog Search. Now he’s at Circle, the company behind the USDC stablecoin (the second largest globally by market capitalization).
Chandhok’s two decades at some of the world’s most successful consumer-facing companies have prepared him well for heading up the stablecoin movement as Circle’s chief product and technology officer. He believes that consumer focus is what separates Circle from less-successful stablecoin providers.
Chandhok has had an insider’s view of some of this century’s most significant tech developments. In the early 2000s, he spent three years at Microsoft building its first enterprise storage and virtualization products. At Google, he was a product lead on Google Blog Search. As an early YouTube employee, he launched the YouTube app on the first iPhone in 2007 and built YouTube Music into the platform’s top revenue driver, with roles spanning mobile, live streaming, subscriptions and original programming. He later shaped Google’s AR strategy for wearables and phones, and served as Meta’s lead for AR glasses.
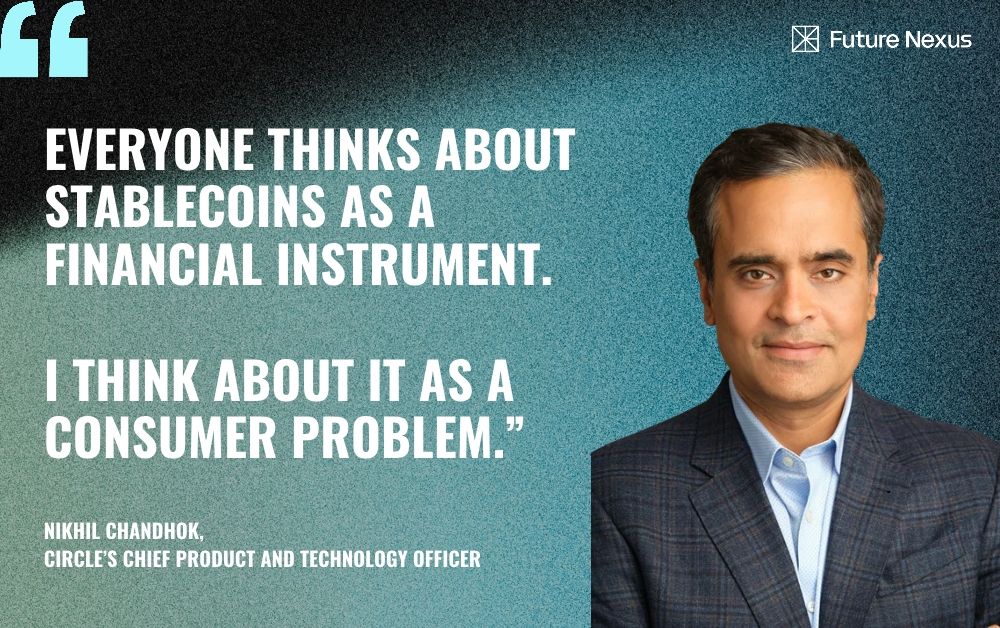
“Everyone thinks about stablecoins as a financial instrument. I think about it as a consumer problem,” Chandhok began.
Money as a human need
Access to money is a basic human need — Chandhok said it’s at the core of what makes human existence possible today.
If we’re to follow the demand, meeting that need means making money available to everyone. Most often this means by phone and in US dollars.
Chandhok said some Americans still don’t grasp how important the dollar is to people outside the 50 states, who view it as an inflation hedge and a way to simplify business transactions.
Exporting US dollars, and the capability to transact in them, fosters the dollar’s position of primacy. It also empowers billions of people financially without requiring them to abandon their local currencies.
Circle is available in more than 100 countries. While some regional patterns are unique, Chandhok sees many universals: people want to save, send remittances and easily complete business payments.
A Brazilian entrepreneur trying to pay a Chinese supplier has a liquidity issue most easily solved with dollars. Small and mid-sized businesses don’t get competitive rates, and dollars might be scarce. With stablecoins, as soon as the product reaches port, the transfer is initiated and the shipment released soon after. No more illiquid capital.
Lessons on building for consumers
Chandhok shared two design lessons he’s gleaned from nearly a quarter-century of innovation.
1. Keep the product simple.
Consumers abhor complexity. They know money when it’s either in their bank or their wallet.
On-chain funds add a new layer of possibility. How do you make this option ubiquitous? Don’t explain how it works — the bar for changing consumer behavior is too high. Just deliver value.
International users struggled to hold dollars; now they don’t. There’s your 10X or 100X improvement. It’s a different story stateside, where consumers already have many payment options
“Knowing where you are on the utility curve for the user really matters,” Chandhok said. “Explain that very clearly.”
2. Ensure universal network utility
As he reflected on past projects, Chandhok said every member benefited from the network’s growth. With stablecoins, if a receiver accepts USDC, all network members benefit; they can become senders and receivers to everyone else.
“If you reason about the problem as a network utility instead of treating it as a financial tool, you build products differently, you reason about the products differently, you drive the incentive programs differently because you care about the health of the network,” Chandhok said, adding that this mistake has tripped up many a design team.
Settlement, programmability, and the agentic era
Chandhok said settlement times are where traditional payment systems end and stablecoins begin: instantaneous payment without intermediary risk and that scales globally.
The programmability, which increases utility, is what further excites Chandhok. It becomes especially handy as we enter the agentic era. Chandhok said discussions both at Circle and throughout the industry focus on the differences between agentic- and human-run companies. Someone starting from scratch today will design a series of agents and fill the gaps with people.
“If that becomes a factor in building companies, and I believe that to be true, then these autonomous agents will need the ability to handle money,” Chandhok said.
Innovating the dollar
As the conversation wound to a close, Chandhok returned to the importance of exporting the dollar and the continued impact of the GENIUS Act, the 2025 law that created the first US federal rules for dollar-backed stablecoins, reinforcing American financial leadership.
“If we’re concerned about the dollar and its place in the world, bringing innovation to the dollar is really important,” Chandhok said. “That’s what we present. Now you can do things with the dollar that you can’t with other currencies.”